
The most promising fintech app ideas for startups are a personal finance management app, a cryptocurrency trading platform, an expense management app, an invoicing and accounts receivable management app, a savings and investment app, a business credit scoring app, and an insurance app. The strongest of them are built around a specific problem and solve it in a way that feels faster, clearer, or more trustworthy than existing options.
Finding that idea means answering hard questions: what gaps exist in the market, how technology can improve financial processes, and which features users will genuinely value. For each idea, we list the key features, monetization strategies, and an existing app to learn from, such as YNAB, Coinbase, Expensify, or Robinhood.
Below, we cover the rise of fintech apps and the trends shaping them, the top fintech app ideas for startups, real-life fintech cases from Shakuro, and how to choose the right fintech app for your startup.
Key takeaways
- In 2026, the strongest fintech ideas are usually built around a specific problem, not a vague promise to “disrupt finance.”
- AI is changing fintech from both sides: it improves the customer experience and helps teams handle risk, support, and operations more efficiently.
- The best startup ideas are often not the most exotic ones. They are the ones that solve a real need in a way that feels faster, clearer, or more trustworthy than existing options.
The rise of fintech apps
To come up with a good idea, first, we need to dwell on the evolution of the fintech industry. How it emerged and what changes it underwent.
The evolution of fintech apps
Over the past decade, we have witnessed a remarkable transformation driven by technological advancements and shifts in consumer behavior.
Initially, a fintech app emerged as a simple online banking and payment processing tool. As technology advanced, these applications expanded to include comprehensive services such as invoicing, accounting, and cash flow management. This evolution has made financial services more accessible to small business owners without the resources to engage with traditional banking institutions.
1980s-1990s: Origins
The roots of fintech can be traced back to the 1980s with the introduction of electronic trading platforms and the use of algorithms in trading. The launch of the first online banking services in the 1990s marked a pivotal moment in financial services.
2000s: Emergence of online financial services
In the early 2000s, the rise of the Internet led to the appearance of various online financial services. Companies like PayPal emerged, revolutionizing online payments and paving the way for peer-to-peer payments.
2010s: The rise of startups
The 2010s saw a surge in fintech app development, driven by the need for more accessible and efficient financial services. Mobile banking, robo-advisors, and crowdfunding platforms began to gain popularity. Venture capital investments in fintech exploded, allowing numerous startups to flourish.
2020s: Mainstream adoption and regulation
As fintech matured, established financial institutions began to collaborate with fintech firms, leading to increased innovation. Regulatory challenges emerged, prompting governments to create frameworks for fintech operations. The COVID-19 pandemic accelerated the adoption of digital finance solutions worldwide.
Fintech impact on small businesses
One of the most significant impacts is the democratization of financial services. A fintech app typically offers lower fees, faster transactions, and more user-friendly experiences compared to conventional banks. Small businesses can manage their finances more effectively and affordably, fostering growth and innovation.
Additionally, the rise of alternative lending platforms has been a game changer. Companies can now access funding through peer-to-peer lending or crowdfunding platforms that bypass traditional credit assessments. This has allowed many entrepreneurs to secure capital that may have been previously inaccessible, driving entrepreneurship and enhancing market competition.
Moreover, fintech applications have improved financial literacy and management capabilities among small business owners. Many apps provide valuable insights and analytics, allowing entrepreneurs to make data-driven decisions. With enhanced visibility into their financial health, small businesses can better forecast cash flow, manage expenses, and plan for growth.
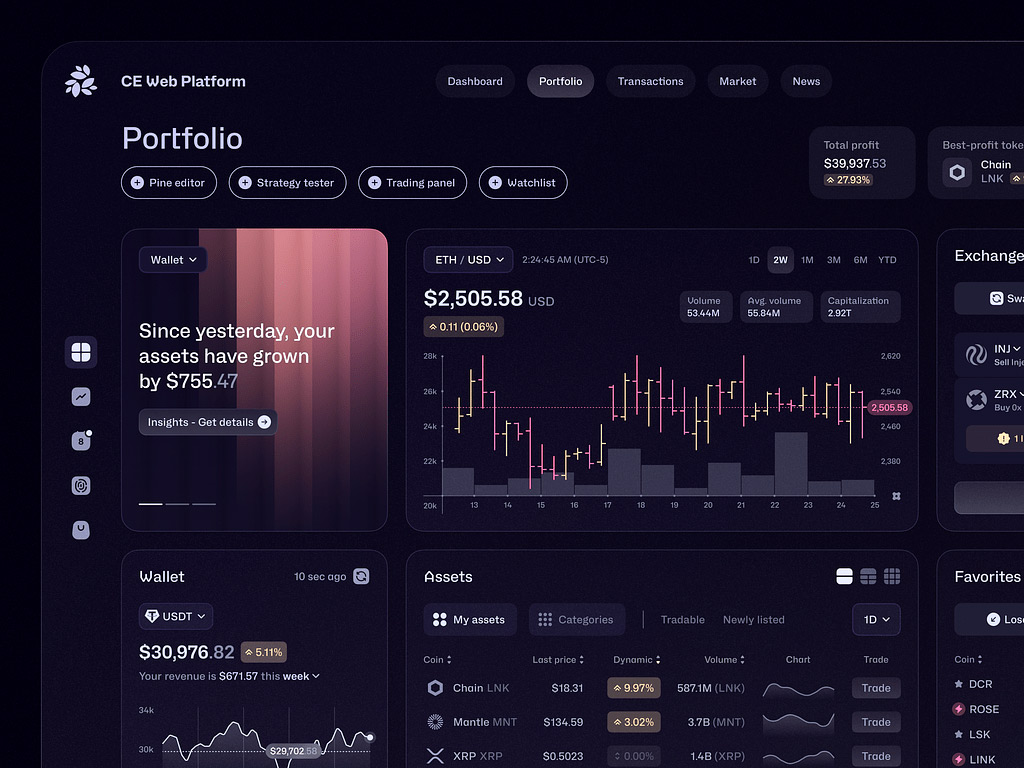
Crypto Exchange Web Platform by Conceptzilla
What makes a fintech idea viable today
A promising fintech idea connects a specific customer problem with a service the team can deliver reliably and operate sustainably. Technologies such as AI, open banking, and embedded finance can support that service, but their value depends on the workflow they improve.
Before choosing features, evaluate the idea against a few practical criteria.
A clear audience and a recurring problem
Define who experiences the problem, how they handle it now, and what makes the current process difficult. “Helping people manage money” is broad. Helping independent consultants track overdue invoices gives the team a clearer starting point.
Consider how often the problem occurs and what happens when it remains unresolved. A monthly workflow can justify a product if it carries enough administrative effort, financial impact, or uncertainty. Daily engagement is not the right success measure for every financial service.
Access to the data and services the product needs
Check whether essential data is available for the intended customers, institutions, and countries. Evaluate coverage, update frequency, connection reliability, and provider costs before making integrations central to the value proposition.
The product must also work when information is incomplete or delayed. Users need to understand when data was last updated, which actions remain pending, and how to recover from a disconnected account.
If the workflow depends on a financial partner, confirm that its supported services, onboarding requirements, and commercial terms fit the proposed launch.
A reason to pay and sustainable operating costs
Identify the buyer and the outcome they would pay for. In a business expense app, employees submit receipts, but a finance manager may control the purchasing decision.
Estimate the cost of delivering that outcome. Include data access, payment processing where relevant, document extraction, infrastructure, customer support, and partner fees. Usage growth can increase both income and service costs.
Test whether the proposed pricing supports the expected workload. A useful feature becomes a stronger business opportunity when customers value it enough to cover its delivery and ongoing improvement.
AI with a defined job and measurable quality
Use AI where it improves a specific task, such as extracting receipt details, suggesting transaction categories, or helping users find information in documents.
Define how quality will be assessed and what happens when the output is uncertain or wrong. Receipt extraction, for example, needs a correction path and a way to measure errors, processing time, and cost.
Compare the AI-assisted workflow with a simpler alternative. Measure whether it reduces effort without creating enough review work to cancel out the benefit.
Evidence that supports the next investment
Choose a small experiment around the idea’s biggest uncertainty. Interviews can clarify the problem, a prototype can test comprehension, and an integration PoC can investigate feasibility. A working pilot can show whether customers complete the workflow and return when the need arises.
Set the evidence and decision criteria before the test. Useful signals might include invoices processed, approval time, repeat use across billing cycles, or willingness to pay.
Use the results to decide whether to expand the pilot, improve the workflow, change an assumption, or stop pursuing the current concept.
Top fintech app ideas for startups
Personal finance management app
It can empower users to take control of their finances by providing them with tools to budget, track expenses, set financial goals, and improve their overall financial literacy.
This idea is a valuable startup opportunity to address consumers’ growing need for financial literacy and management tools. By leveraging technology to provide personalized insights, you can help individuals achieve their goals while fostering healthier financial habits.

Mobile Banking App by Conceptzilla
What are the key features?
- Budgeting Tool:
Allow users to set personalized budgets across different categories (e.g., groceries, entertainment, utilities) and track their spending in real-time. Also, the tool alerts people when they are nearing their budget limits.
- Expense Tracking:
Automate transaction tracking by linking users’ bank accounts and credit cards. Provide insights into spending patterns with visual graphs and reports to help people understand their financial habits.
- Savings Goals:
Users can set specific savings goals (e.g., vacation, emergency fund, down payment for a house) and track their progress. The fintech app can suggest ways to cut unnecessary spending to help meet those goals faster.
- Personalized Financial Insights:
Analyze users’ financial data and offer tailored insights, such as recommendations for better spending habits or savings suggestions based on their unique situation. To manage large data amounts, you can leverage Artificial Intelligence.
- Bill Reminders and Payments:
Implement a reminder system for upcoming bills and offer an option to pay bills directly through the app, ensuring users never miss a payment and avoid late fees.
- Investment Tracking:
Include features to track investments, providing users with an overview of their portfolio performance and suggesting rebalancing strategies when necessary.
- Financial Education Resources:
Offer educational content like articles, videos, and webinars to help users improve their financial literacy. Cover topics like credit scores, investment basics, and savings strategies.
- Gamification Elements:
Incorporate gamification techniques to encourage users to engage actively with the app. Offer rewards for reaching milestones, completing challenges, or consistently staying within budget.
- Community Support:
Create a community or support group within the app where users can share tips, ask questions, and motivate each other on their financial journeys.
- Data Security and Privacy:
During fintech app development, implement strong security measures to protect users’ financial information. Employ encryption and offer transparent privacy policies to build trust.
Monetization strategies:
- Freemium Model: Offer a basic version of the app for free, with the option to upgrade to a premium subscription that includes advanced features like comprehensive financial analysis, personalized consultation, ad-free usage, etc.
- Affiliate Partnerships: Collaborate with financial institutions and services (e.g., credit card companies, and loan providers) to earn commission through referrals when users take advantage of their offerings.
- In-app Purchases: Provide additional features or content (e.g., financial workshops, and one-on-one coaching sessions) as in-app purchases.
An example of a personal financial app is YNAB (You Need A Budget). It helps users manage their finances with zero-based budgeting. The app emphasizes a proactive approach to budgeting, allowing individuals to allocate their income toward specific spending categories.
Cryptocurrency trading platform
These fintech app ideas facilitate the buying, selling, and exchanging of various cryptocurrencies, providing users with advanced trading tools to navigate the digital asset market.
And you can capitalize on the growing interest in digital assets. By focusing on user experience, security, and comprehensive educational resources, your platform can attract a diverse range of users, from novices to seasoned investors, and help them successfully navigate the evolving world of cryptocurrencies.
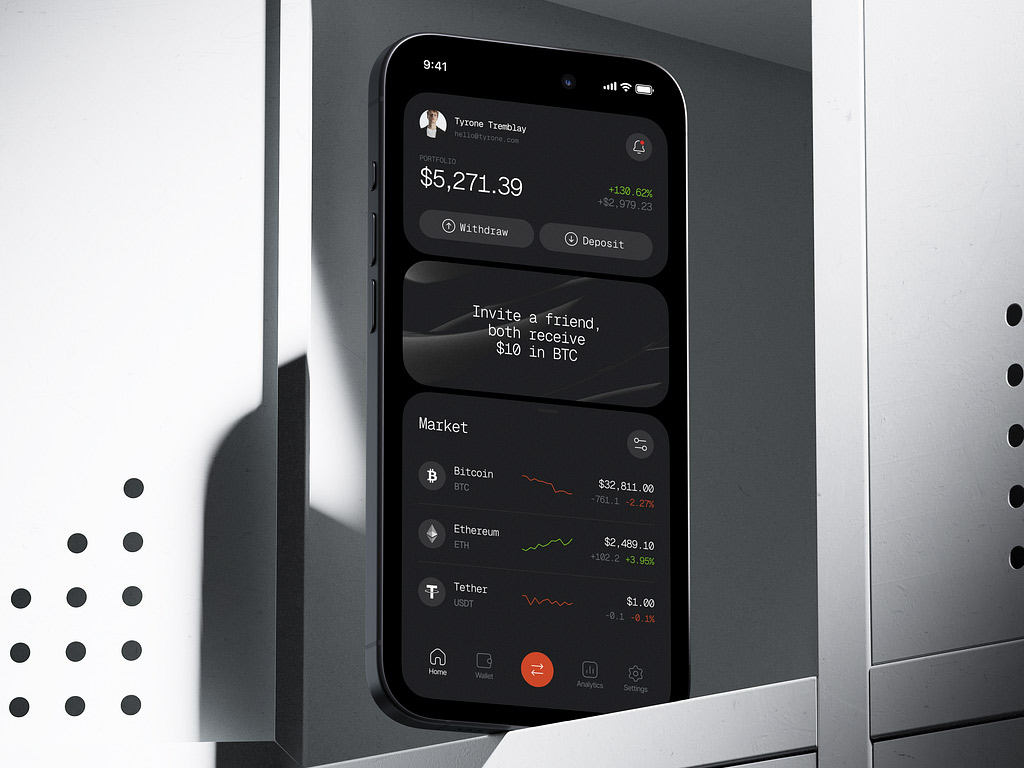
Crypto App Design Concept by Conceptzilla
What are the key features?
- Advanced Trading Tools:
Offer advanced charting tools, technical analysis indicators, and market depth data that cater to seasoned traders looking for comprehensive market insights.
However, if your target audience is mostly beginner traders, implement simplified tools and educational resources into your fintech app.
- Multiple Cryptocurrency Support:
Support a wide range of cryptocurrencies, including major ones like Bitcoin, Ethereum, and newer altcoins. Regularly update the platform with new listings based on market demand.
- Wallet Integration:
Integrate secure in-app wallets for users to store their cryptocurrencies safely within the platform, minimizing the need to rely on external wallets.
- Staking and Yield Farming Options:
Introduce features that allow users to stake cryptocurrencies or participate in yield farming, enabling them to earn rewards on their holdings.
- Security Features:
Implement robust security measures, such as two-factor authentication, cold storage for funds, and regular security audits to ensure user data and assets are protected.
- Community Engagement:
Create community forums and chat features where users can share insights, discuss market trends, and seek advice from more experienced traders.
- Customer Support:
Offer responsive customer support through live chat, email, and a comprehensive FAQ section to address user queries or issues promptly.
Monetization strategies:
- Transaction Fees: Charge a small fee for each transaction executed on the platform, which can vary based on the trading volume or user tier (e.g., higher tiers have lower fees).
- Subscription Model: Introduce tiered subscription plans that offer additional features, such as lower fees, access to premium trading tools, or exclusive market reports.
- Staking and Yield Fees: Collect a small fee on returns earned through staking or yield farming features offered on the platform.
- Affiliate Marketing: Partner with crypto-related services and earn commissions on referrals, such as exchanges, wallets, or educational platforms.
An example of a cryptocurrency trading app is Coinbase. It is one of the largest cryptocurrency exchanges in the world. The app allows users to buy, sell, and manage various cryptocurrencies such as Bitcoin, Ethereum, and many others. At the same time, it is designed for both beginners and experienced traders.
Business expense management app
A business expense management app helps employees submit expenses, managers review them, and finance teams prepare accurate records for reimbursement and accounting.
Start with a specific audience, such as small agencies, field service companies, or distributed teams. Their needs differ: one business may struggle with missing receipts, while another needs to allocate expenses across clients and projects.
The product opportunity is to make that recurring workflow easier to complete and supervise.
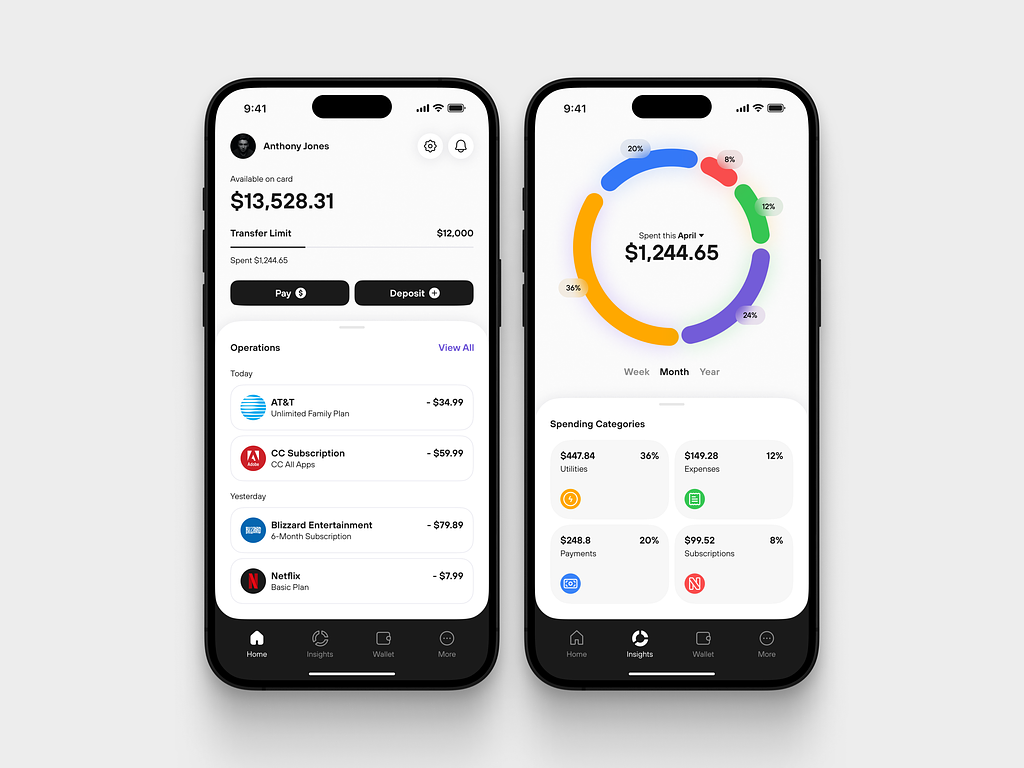
Finance Management Mobile App Design by Conceptzilla
What are the key features?
Receipt capture and expense submission
Let employees upload receipts and record the merchant, date, amount, currency, category, and business purpose. If receipt scanning extracts these fields automatically, allow users to review and correct them before submission.
Company policies and basic checks
Support configurable requirements, such as mandatory receipts, spending limits, and project codes. Flag missing information and possible duplicates for review. Keep policy exceptions visible and provide a way to explain or approve them.
Approval workflows
Route submitted expenses to the appropriate reviewer. Managers should be able to approve, reject, or request changes, with a recorded explanation. Employee, manager, and finance roles need appropriate access to records and actions.
Reimbursement status
Distinguish expenses awaiting approval from those approved, scheduled for reimbursement, and paid. Manager approval should not automatically mark an expense as reimbursed.
An initial product can track payments completed through an existing process. Automated payouts can follow through a suitable payment partner.
Accounting exports and reconciliation
Provide a structured export with the fields the accountant needs. Separate employee-paid expenses from company-card purchases so the same transaction is not reimbursed twice.
Direct accounting integrations and corporate card imports can be added when they address a validated customer requirement.
Operational visibility
Show pending approvals, missing receipts, unresolved exceptions, and amounts awaiting reimbursement. Preserve a history of important changes so finance teams can investigate discrepancies.
The core workflow should be:
Capture an expense → Submit it → Review it → Approve or return it → Track reimbursement → Export or reconcile the record.
Monetization strategies
A new product could charge a subscription per organization or active user, with additional tiers for approval rules, integrations, and reporting. Larger customers may also pay for onboarding, data migration, or workflow configuration.
Tie pricing to a clear operational benefit, such as less administrative work or faster expense processing. Validate willingness to pay with the person who controls the budget, alongside usability testing with employees and reviewers.
Example to Learn From: Expensify
Expensify combines receipt scanning, expense submission, approvals, reimbursement, and accounting connections. Its documented capabilities also include customizable workflows and corporate card imports.
The product lesson is the connection between employee input and finance-team operations. A focused startup could serve a particular industry, accounting workflow, or approval requirement without reproducing the entire platform.
How to Validate the Idea
Pilot the product with a small group of businesses. Measure submission-to-approval time, incomplete submissions, correction requests, and finance-team processing effort. Compare results with their previous workflow and check whether teams continue using the app across subsequent expense cycles.
Invoicing and accounts receivable management
Freelancers, agencies, and small service businesses often manage invoices, payment reminders, and customer records across several tools. An invoicing and accounts receivable app can bring these tasks into one workflow, helping users understand what customers owe, when payments are due, and which invoices need attention.
Start with a specific audience and its billing process. For example, a small agency may need milestone invoices and shared payment tracking, while an independent consultant may prioritize recurring invoices and simple reminders.

Zoho Invoice app
What are the key features?
Invoice creation and delivery
Let users maintain customer records, create invoices, set payment terms, and send documents through a consistent process. Include the fields required for the initial target market and clearly distinguish drafts, issued invoices, and canceled documents.
Payment tracking
Show the original amount, payments received, and remaining balance. Support partial payments and manual recording of payments made outside the app. If online payments are included, use a suitable payment provider and distinguish processing, failed, and confirmed payments.
Reminders and follow-up
Allow users to schedule reminders before and after the due date. Pause reminders when an invoice is paid or disputed, and provide a communication history so team members can see what has already happened.
Receivables overview
Display outstanding and overdue amounts, upcoming due dates, and balances by customer. An aging report can group unpaid invoices by how long they have been overdue, helping users prioritize follow-up.
Exports and access controls
Provide an export for the accountant and appropriate permissions for team members. Keep a record of important changes, including adjustments to invoice amounts and payment status.
The initial workflow should be complete:
Create an invoice → Send it → Track its status → Follow up when needed → Record and reconcile payment.
Accounting integrations, automated reconciliation, and more advanced billing arrangements can follow when customer demand justifies them.
Monetization options
A new product could charge a subscription per business, with tiers based on team access, invoice volume, automation, or integrations. Paid onboarding and data migration may also suit customers moving from spreadsheets or older systems.
The strongest paid offering should address a specific workflow problem. Test whether customers will pay for reduced administrative effort, better collaboration, or clearer receivables visibility.
Payment processing charges should be explained separately. Any platform transaction fee needs a clear commercial arrangement with the payment provider.
Example to learn from: Zoho Invoice
Zoho Invoice provides invoice creation, online payment collection through supported gateways, and automated payment reminders. Its documented features also include recurring invoices, customer statements, and a customer portal.
The product lesson is the connection between creating an invoice and managing its collection. A useful startup opportunity could focus on a particular industry, approval process, or integration requirement within that workflow.
Financing against unpaid invoices would introduce a separate service model involving funding arrangements and additional responsibilities.
How to validate the idea
Run a pilot with businesses that regularly issue invoices. Measure how many complete the workflow, how much time they spend on administration, and whether they return for the next billing cycle. Compare overdue balances and collection times cautiously: customer payment behavior can change for reasons outside the app.
Savings and investment app
Apart from a simple saving application, you can opt for an investment app. The fintech app allows users to manage their savings and investment goals in a user-friendly and engaging way. You can help individuals learn about investing, automate their savings, and provide personalized investment advice, ultimately encouraging better financial habits.

Abyss app by Conceptzilla
What are the key features?
- Goal-Based Savings:
Add options to set specific savings goals (e.g., vacation, emergency fund, home purchase) and track the user’s progress toward achieving those goals.
- Automated Savings Plans:
Provide features that allow users to set up automated transfers from their checking accounts to their savings accounts based on customizable rules (e.g., rounding up purchases, and setting fixed monthly contributions).
- Diverse Investment Options:
Offer various investment opportunities, such as stocks, ETFs, mutual funds, or robo-advisory services, allowing users to choose investment products based on their risk tolerance and investment goals.
- User Education:
Incorporate educational resources, such as articles, videos, and tutorials, to help users understand investment fundamentals, market trends, and strategies for successful investing.
- Portfolio Diversification:
Provide personalized investment recommendations that encourage diversification across different asset classes to minimize risk and enhance returns.
- Impact Investing Options:
Introduce sustainable and socially responsible investment choices, appealing to users interested in making a positive social or environmental impact while investing.
- Real-Time Performance Tracking:
Allow users to monitor the performance of their savings and investments in real-time with easy-to-read graphs and analytics.
- Risk Assessment Tools:
Integrate features that assess users’ risk tolerance and financial situations to create personalized investment strategies tailored to their needs.
- Community Features:
Foster a community or forum where users can share experiences, tips, and insights about saving and investing, which encourages engagement and learning.
- Security and Privacy:
Ensure robust security measures to protect businesses’ financial information, including encryption and two-factor authentication.
Monetization strategies:
- Transaction Fees: Charge a small fee for each transaction made within the fintech app, such as buying or selling investments.
- Subscription Model: Offer premium features or advanced investment tools through a monthly or annual subscription plan.
- Advisory Fees: If providing managed investment services, charge a percentage-based fee on assets under management (AUM).
- Affiliate Partnerships: Form partnerships with banks or financial institutions to earn referral commissions for users who open accounts through the app.
- Educational Courses: Offer paid access to in-depth courses or webinars that cover advanced investment topics, financial planning, or wealth management strategies.
An example of an investment app is Robinhood. It combines stock trading with investment, offering commission-free trading of stocks and ETFs, in-app educational courses, and branded cash cards.
Business credit scoring app
The fintech app idea aims to provide small and medium-sized enterprises (SMEs) and startups with a comprehensive understanding of their creditworthiness. You offer real-time credit scores, insights, and actionable advice to help businesses maintain healthy credit profiles, secure financing, and make informed financial decisions.

Nav credit scoring app
What are the key features?
- Real-Time Credit Scoring:
Add instant access to business credit scores based on various factors such as payment history, credit utilization, financial health, and industry benchmarks.
- Credit Monitoring:
Enable real-time monitoring of users’ credit profiles, alerting them to significant changes, potential fraud, or important updates that could affect their creditworthiness.
- Detailed Credit Reports:
Offer comprehensive credit reports that break down the components of a business’s credit score, including payment history, public records, and credit inquiries, helping users understand the factors affecting their score.
- Financial Health Insights:
Integrate tools to analyze business financial statements and cash flow, providing insights on how to improve credit health and financial performance.
- Actionable Recommendations:
Deliver personalized suggestions for improving credit scores, such as timely payments, reducing debt, and managing credit utilization more effectively.
- Educational Resources:
Include articles, videos, and tips on understanding business credit scores, the importance of maintaining a good credit profile, and how to prepare for loan applications.
- Integration with Accounting Software:
Allow seamless integration with popular accounting software to automatically track and report business financials, making it easier for users to manage their credit health.
- Peer Comparison:
Offer benchmarking tools that allow users to compare their credit scores and financial performance against industry peers, helping them identify areas for improvement.
- Loan Application Tools:
Facilitate a streamlined loan application process by providing pre-qualification assessments to determine the best financing options based on users’ credit profiles.
- Security and Privacy:
Implement strong security protocols to protect sensitive business information, including encryption, multi-factor authentication, and compliance with data protection regulations.
Monetization strategies
- Subscription Model: Charge users a monthly or annual fee for premium features, such as detailed credit reports, monitoring alerts, and personalized consulting services.
- Affiliate Partnerships: Collaborate with lenders and financial institutions to offer referral programs, earning commissions for each loan application generated through the app.
- Consulting Services: Provide premium consulting services for businesses seeking tailored advice on improving their credit scores or navigating the loan application process.
- Educational Courses: Offer paid resources, webinars, or courses focused on financial management, credit improvement strategies, and business growth.
- Data Analytics: Aggregate anonymized data for market research and sell insights to financial institutions looking to understand trends and behaviors among SMEs.
An example of a business credit scoring app is Nav. It helps you manage your company credit, enhance your overall financial health, and obtain the finance you require to flourish.
Insurance app
The fintech app idea revolutionizes the way individuals and businesses interact with their insurance policies. The app simplifies the buying process, enhances customer engagement, and streamlines claims management, all while using advanced technologies to provide personalized insurance solutions.
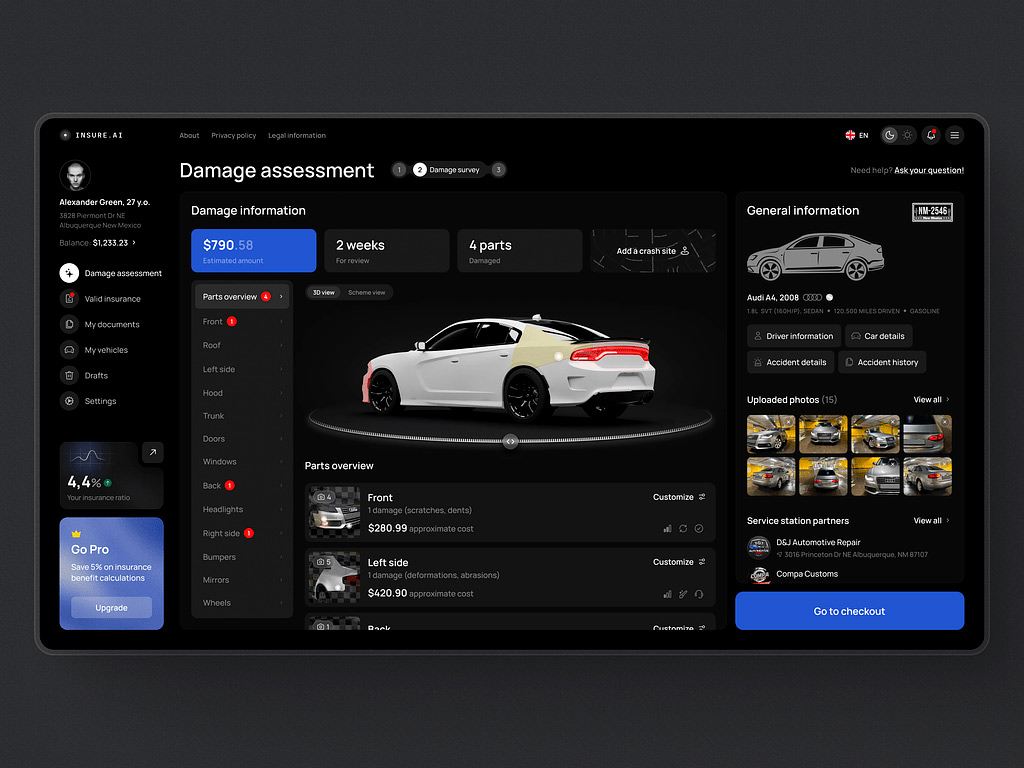
AI Insurance Web Design Concept by Shakuro
What are the key features?
- Instant Quotes:
Allow users to receive instant insurance quotes for various types of coverage (auto, home, health, business) by entering basic information, making it easier to compare options.
- Policy Management:
Provide a user-friendly dashboard where customers can easily view, manage, and renew their insurance policies, track payment history, and access policy documents.
- Claims Submission:
Streamline claims process where users can file claims directly through the app, upload necessary documents, and track the status of their claims in real-time.
- Claims Assistance:
Leverage fintech app trends and incorporate an AI chatbot that can guide users through the claims process, answer common questions, and provide assistance with documentation.
- Customizable Coverage:
Offer personalized policy recommendations based on user profiles, preferences, and circumstances, allowing customers to tailor coverage to their specific needs.
- Risk Assessment Tools:
Include tools that analyze users’ risk factors and provide insights on how to reduce risks (e.g., home safety tips, safe driving advice), which could potentially lower insurance premiums.
- Educational Resources:
Provide a library of articles, guides, and videos that educate users about different types of insurance, policy details, and best practices for choosing coverage.
- Multi-Policy Discounts:
Encourage users to bundle their insurance policies (e.g., auto and home) through discounts or rewards, increasing customer loyalty and retention.
- Referral Program:
Incentivize users to refer friends and family to the app by offering discounts or cash rewards for successful referrals, expanding your user base.
- Integration with Financial Planning Tools:
Offer integration with budgeting and financial planning tools to help users understand how insurance costs fit into their overall financial strategy.
Monetization strategies:
- Commission-Based Model: Earn commissions on policy sales and renewals through partnerships with insurance providers, acting as an aggregator for multiple insurance products.
- Premium Membership: Introduce a subscription model that offers users access to premium features, such as personalized consulting, advanced risk assessments, or loyalty rewards.
- Educational Workshops: Conduct paid online workshops or webinars focusing on personal finance, risk management, and understanding insurance, appealing to users seeking in-depth knowledge.
- Sponsored Content: Collaborate with insurers for sponsored content or featured listings within the app, promoting their products to your user base.
- Data Analytics Services: Offer aggregated data insights to insurers and financial institutions, helping them understand market trends and customer preferences.
An example of an insurance app is Digit Insurance. All processes there are paperless, with auto-renewal, simplified policies and claims. There are insurances for transport, healthcare, and property.
Define your financial service model before building
A fintech idea becomes easier to scope when you define exactly what the product does, who provides the underlying financial service, and where it operates.
Start with the customer journey. Identify whether the app displays information, recommends an action, submits an instruction, moves money, or holds assets. Each activity introduces different product requirements, partner dependencies, and potential regulatory obligations.
Separate activities that require different operating models
Features that look similar on a screen can involve very different responsibilities.
| Product area | Distinctions to make before development |
| Personal finance | Importing and displaying transactions; initiating payments; holding customer funds |
| Business expenses | Collecting receipts and approving expenses; executing reimbursements; issuing company cards |
| Invoicing | Creating invoices and tracking receivables; arranging financing; providing the funding |
| Investments | Tracking a portfolio; providing personalized recommendations; executing orders; managing assets |
| Cryptocurrency | Displaying balances and market data; executing trades; controlling private keys or safeguarding assets |
| Credit | Displaying credit information; preparing applications; making lending decisions; providing capital |
| Insurance | Organizing policy documents; recommending or selling coverage; underwriting policies; deciding claims |
Use these distinctions to define the initial product boundary. Adding payment execution or personalized advice can change the operating model even when the interface change appears small.
Confirm requirements for the intended market
Define the initial countries, customer types, and activities before choosing providers or finalizing the MVP.
“Read-only” does not automatically mean an activity falls outside financial regulation. In the UK, for example, account information services and payment initiation services have distinct registration or authorization requirements.
Automation also does not remove the need to assess the service being provided. The SEC’s guidance on robo-advisers addresses obligations associated with algorithm-based investment advice, including disclosures and compliance.
Confirm the applicable requirements with qualified local advisers and prospective partners. The result should inform the scope, launch market, contracts, and delivery plan.
Assign responsibilities between the startup and its partners
A banking, payment, brokerage, lending, or insurance partner can provide important infrastructure. Document which activities the partner performs and which remain with your business.
Before integration work begins, agree on:
- Who contracts with the customer and provides each financial service.
- Who holds funds or assets and maintains the authoritative transaction records.
- Who performs any required identity, business, fraud, or risk checks.
- Who handles failed transactions, refunds, reconciliation, and complaints.
- Who manages data access, permissions, retention, and incident response.
- What happens when an integration becomes unavailable or the partnership ends.
An API connection provides technical access to a service. The commercial and operational arrangements must also support the intended customer journey.
Keep the MVP within a deliberate boundary
Choose the smallest complete workflow that tests the product’s value within the agreed service model.
For example, a savings-planning MVP might help users set goals and monitor progress using imported data. Automated transfers would introduce a separate workflow involving payment instructions, authorization, transaction status, and recovery from failures.
Similarly, an expense-management pilot could support submission, approval, and tracking of reimbursements completed through an existing process. Executing payouts can be a later decision supported by a suitable provider.
Make these boundaries visible in the product. Users should understand which actions the app completes and which require another service or person.
Budget for operating the service
Include partner onboarding, integration maintenance, provider fees, customer support, reconciliation, and any required specialist reviews in the operating estimate.
For products involving lending or insurance, distinguish the software delivery budget from capital or funding arrangements. For investment and crypto products, assess custody and execution responsibilities separately from interface development.
Before approving development, prepare a short service-model brief covering the launch market, customer, core workflow, partner roles, data and money flows, unresolved dependencies, and activities deferred beyond the MVP.
Real-life cases of fintech apps from Shakuro
We’ve described seven fintech app ideas that are viral in the industry. However, there is one piece missing: you need a development team experienced in fintech to bring the projects to life.
At Shakuro, we collaborated with several fintech startups on mobile apps, UI/UX design, and branding. Leveraging industry expertise and a cutting-edge toolkit, our team helps businesses build competitive projects.
Here are four real-life industry cases we’re proud of:
ZAD
It is a Shariah-compliant mobile investment platform combining robo-advisor and trading functionality with a comprehensive approach making investments easy and accessible.
Before starting fintech app development, our team conducted an in-depth study of the leading stock trading apps in West Asia and familiarized ourselves with the tenets of Shariah law.
Since the ZAD target audience is everyday customers aged between 20 to 40, we aimed to provide a secure and user-friendly interface, conveyed in a professional and supportive tone, that would instill confidence in the users. We wanted them to feel a sense of security and assurance.
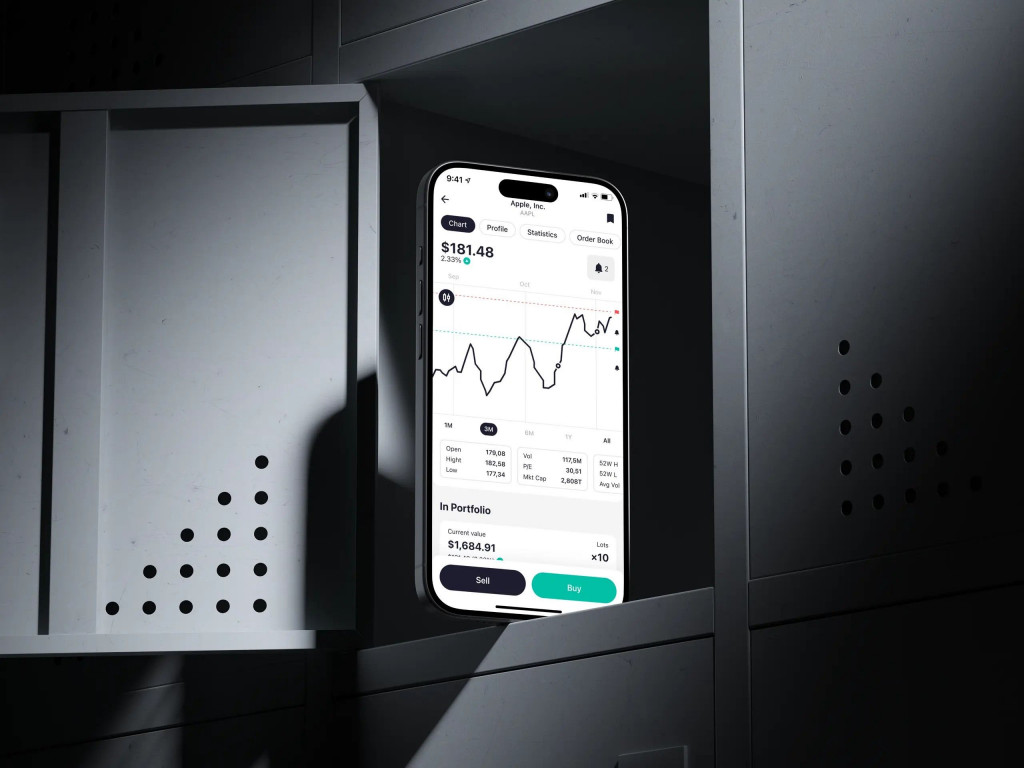
ZAD app by Shakuro
Solio
Solio is a Korean stock trading app that allows users to receive passive income without specific knowledge and experience. The development required a deep analysis of the market, legal and social expectations, and a fair money management system.
We pack robust functionality and complicated infrastructure into a user-friendly interface with familiar app mechanics. The design is approached from the perspective of problem-solving and not just artistic expression, so the team emphasized the balance and individual performance of the stocks the client owns. For beginners, Solio offers pre-made model portfolios and a robo-advisor as a guide.
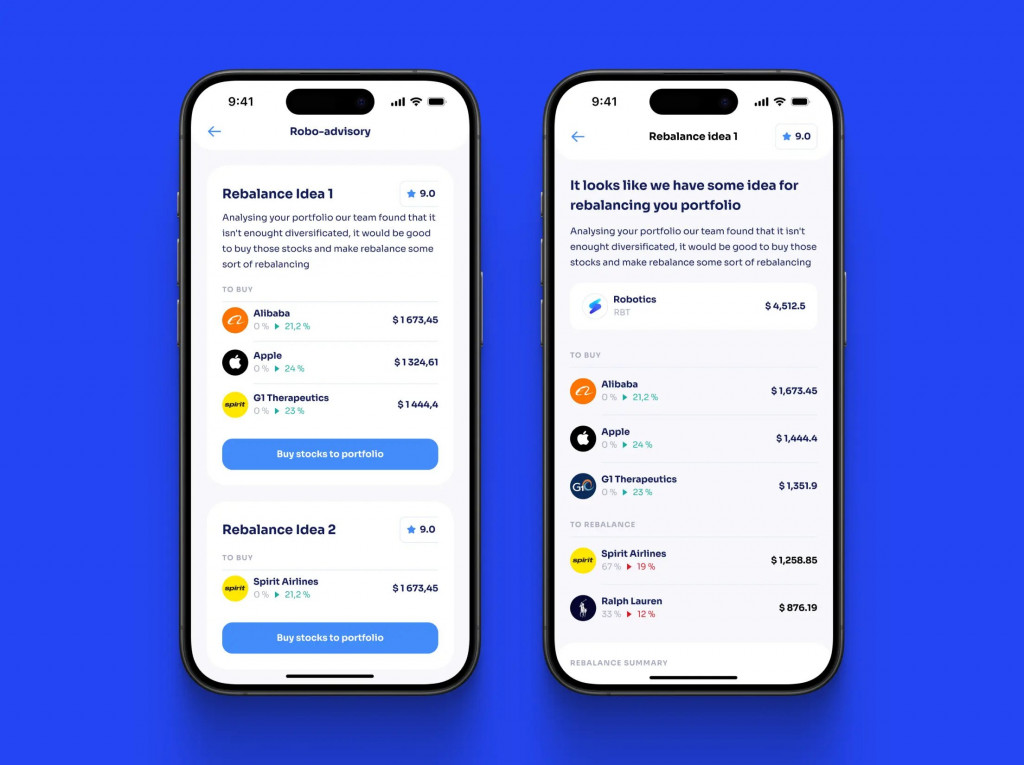
Solio app by Shakuro
Symbolik
Symbolik is a product of the legendary Tom DeMark’s legacy. This is one of the most comprehensive projects we’ve worked on and consists of several tools.
It combines a charting tool, a trading analysis platform, and a social network for traders, investors, and money managers. Together with Symbolik, we redesigned the entire ecosystem with the website: built the Symbolik Social network from scratch, revamped the Symbolik Chart, and breathed new life into the brand’s identity.
Symbolik Social is a social network for traders, where they exchange experiences, know-how, tools, and so on. It is a whole financial community with a peer-generated knowledge base. We built the network from the ground up, taking into account the target audience’s needs and craving for exclusive financial insights.
Symbolik Chart is a professional-grade investment tool and analytics. Traders and investors leverage it to gain market insights, technical analysis, and exclusive add-ons. It offers custom condition builders, price alerts, real-time scans, and extensive data coverage — anything a pro trader might need.
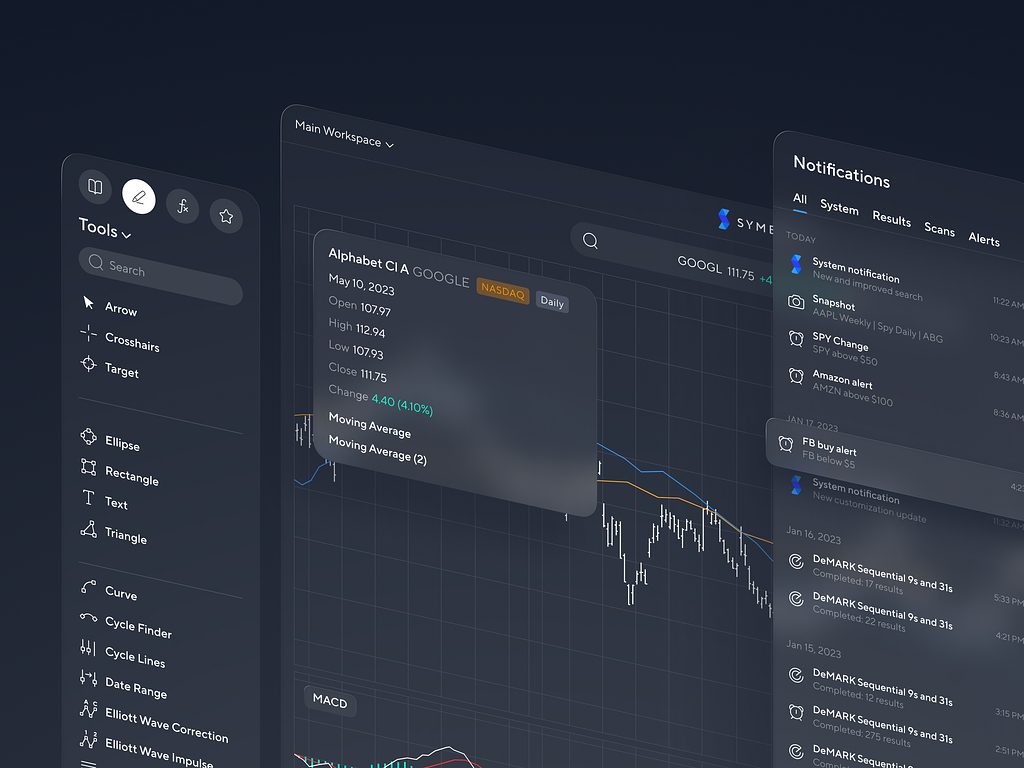
Stock Market Analytics Application by Shakuro
Aurox
It is a leading cryptocurrency trading terminal, market cap website, and issuer of the $URUS token powering an advanced lending and trading system. Apart from comprehensive branding, we also worked on website UI/UX design and mobile app to strengthen the Aurox services.
We opted for ease of use and glanceability so users would have an easier time leveraging the terminal. Spiced up with 3D illustrations and animations, it catches the eye. Also, Aurox needed a motion design for promo reels, and we were happy to provide it.

Aurox app by Shakuro
How to choose the right fintech app for your startup
- Identify Your Target Audience:
Understand who your potential users are. Are you targeting individual consumers, small businesses, or large enterprises? Knowing your audience will help you tailor the app’s features and services to meet their needs.
- Define Your Value Proposition:
Clearly showcase what makes your fintech app unique. What problem does it solve? How does it improve the user experience compared to existing solutions? A strong value proposition will help differentiate your app in a crowded marketplace.
- Research Market Trends:
Stay updated on industry trends and emerging technologies in the fintech sector. Analyze competitors to learn what features are popular and what gaps exist in the market that your app could fill.
- Focus on Compliance and Security:
Regulatory compliance is crucial in fintech. Ensure that your app adheres to legal requirements and industry standards. Prioritize data security to build trust with users, as they are concerned about their financial information.
- Choose the Right Technology Stack:
Select a technology stack that supports your app’s requirements, scalability, and performance. Consider factors like fintech app development cost, speed of deployment, and ease of integration with third-party services.
- UI/UX Design:
Invest in a user-friendly design that provides a seamless experience. A clean, intuitive interface will enhance user satisfaction and retention. Conduct user testing to gather feedback and refine the app’s design.
- Integrate Essential Features:
Identify critical features for your app based on your market research and target audience. This may include budgeting tools, investment tracking, payment processing, or insurance management. However, avoid implementing all features at once and focus on core functionalities for the MVP (Minimum Viable Product).
- Plan for Scalability:
Choose solutions that allow easy updates and scaling as your user base grows. A scalable app can handle increased traffic and functionality without compromising performance.
- Validate with a Prototype:
Create a prototype or wireframe of your app to visualize its layout and features. Use it to gather feedback from potential users and stakeholders before investing in full-scale development.
- Develop a Marketing Strategy:
Plan how you will promote your app once it’s launched. Utilize social media, content marketing, SEO, and partnerships to create awareness and attract users. A well-defined marketing strategy is essential for user acquisition.
- Budget and Funding:
Assess your financial resources and seek funding if needed. Understanding your budget will guide your decisions on development, marketing, and operational costs throughout the startup phase.
- Gather a Strong Team:
Build a diverse team with fintech, development, marketing, and compliance expertise. A strong team is essential for navigating the complexities of this industry and bringing your app to fruition.
FAQ
What are the best fintech app ideas for startups?
Seven ideas stand out: a personal finance management app, a cryptocurrency trading platform, an expense management app, an invoicing and accounts receivable management app, a savings and investment app, a business credit scoring app, and an insurance app. The best choice is not the most exotic one but the idea that solves a real need for a clear audience better than existing products do.
How do fintech apps make money?
Common models are freemium with a paid premium tier, subscription plans, transaction or service fees, affiliate partnerships with banks and lenders, and commissions on policy sales. Investment apps can charge advisory fees on assets under management, and education-focused apps sell courses or webinars. Some apps, with user consent, sell aggregated anonymized data insights to businesses and researchers.
What trends shape fintech app development?
Key fintech app trends are AI and machine learning for personalized advice, credit risk assessment, and fraud detection, blockchain and cryptocurrency integration, open banking, RegTech for compliance, embedded finance in non-financial platforms, digital wallets and contactless payments, peer-to-peer lending, financial wellness tools, sustainable finance, and stronger cybersecurity measures.
How do you choose the right fintech app idea?
Start with your target audience and a clear value proposition: what problem the app solves and why it is better than existing solutions. Research market trends and competitors to find gaps, plan for compliance and security from the start, and focus the MVP on core functionality. Validate the idea with a prototype and feedback from potential users before full-scale development.
What features should a personal finance app have?
A personal finance management app usually needs budgeting tools with alerts, automatic expense tracking linked to bank accounts and cards, savings goals, personalized financial insights, bill reminders and payments, investment tracking, and financial education resources. Gamification and community features keep users engaged, while encryption and transparent privacy policies build the trust that any finance app depends on.
Conclusion
Whether you’re exploring personal finance management, digital banking solutions, investment platforms, or payment processing innovations, the key lies in identifying pain points and delivering tailored solutions that enhance user experience.
The journey requires a creative vision, in-depth market research, and a clear understanding of user needs. By following these principles and continuously adapting to the ever-changing financial environment, startups can position themselves for success and contribute to the future of financial services. With the right approach, your fintech app idea could be the next big breakthrough in the industry, making finance more accessible, efficient, and user-friendly for everyone.
Ready to bring your idea to life but missing a dev team? Contact us and let’s work on your fintech app.
Related reading
- How to Create a FinTech App: A Complete Development Guide
- Banking Software Development: How to Build Modern Digital Banking Platforms
- Insights on Fintech App Development for the Middle East and Near East
- Titans Unveiled: Fastest-Growing Startups Shaping the Future
***
This article was originally published in July, 2024 and was updated in April, 2026 to make it more relevant and comprehensive.